
About Cambs Ely Mortgages
Clear, personal mortgage and protection advice — built around you.
Cambs Ely Mortgages helps individuals, families, landlords and business owners understand their mortgage, property finance and protection options.
Based in Cambridgeshire and working with clients across England, we combine access to more than 200 lenders with personal, straightforward advice designed around your individual circumstances.
Whether you're buying your first home, moving, remortgaging, investing in property or reviewing how you would protect yourself and your family financially, the aim is simple: help you understand your options and make informed decisions with confidence.
Building Blocks for a Brighter Future.
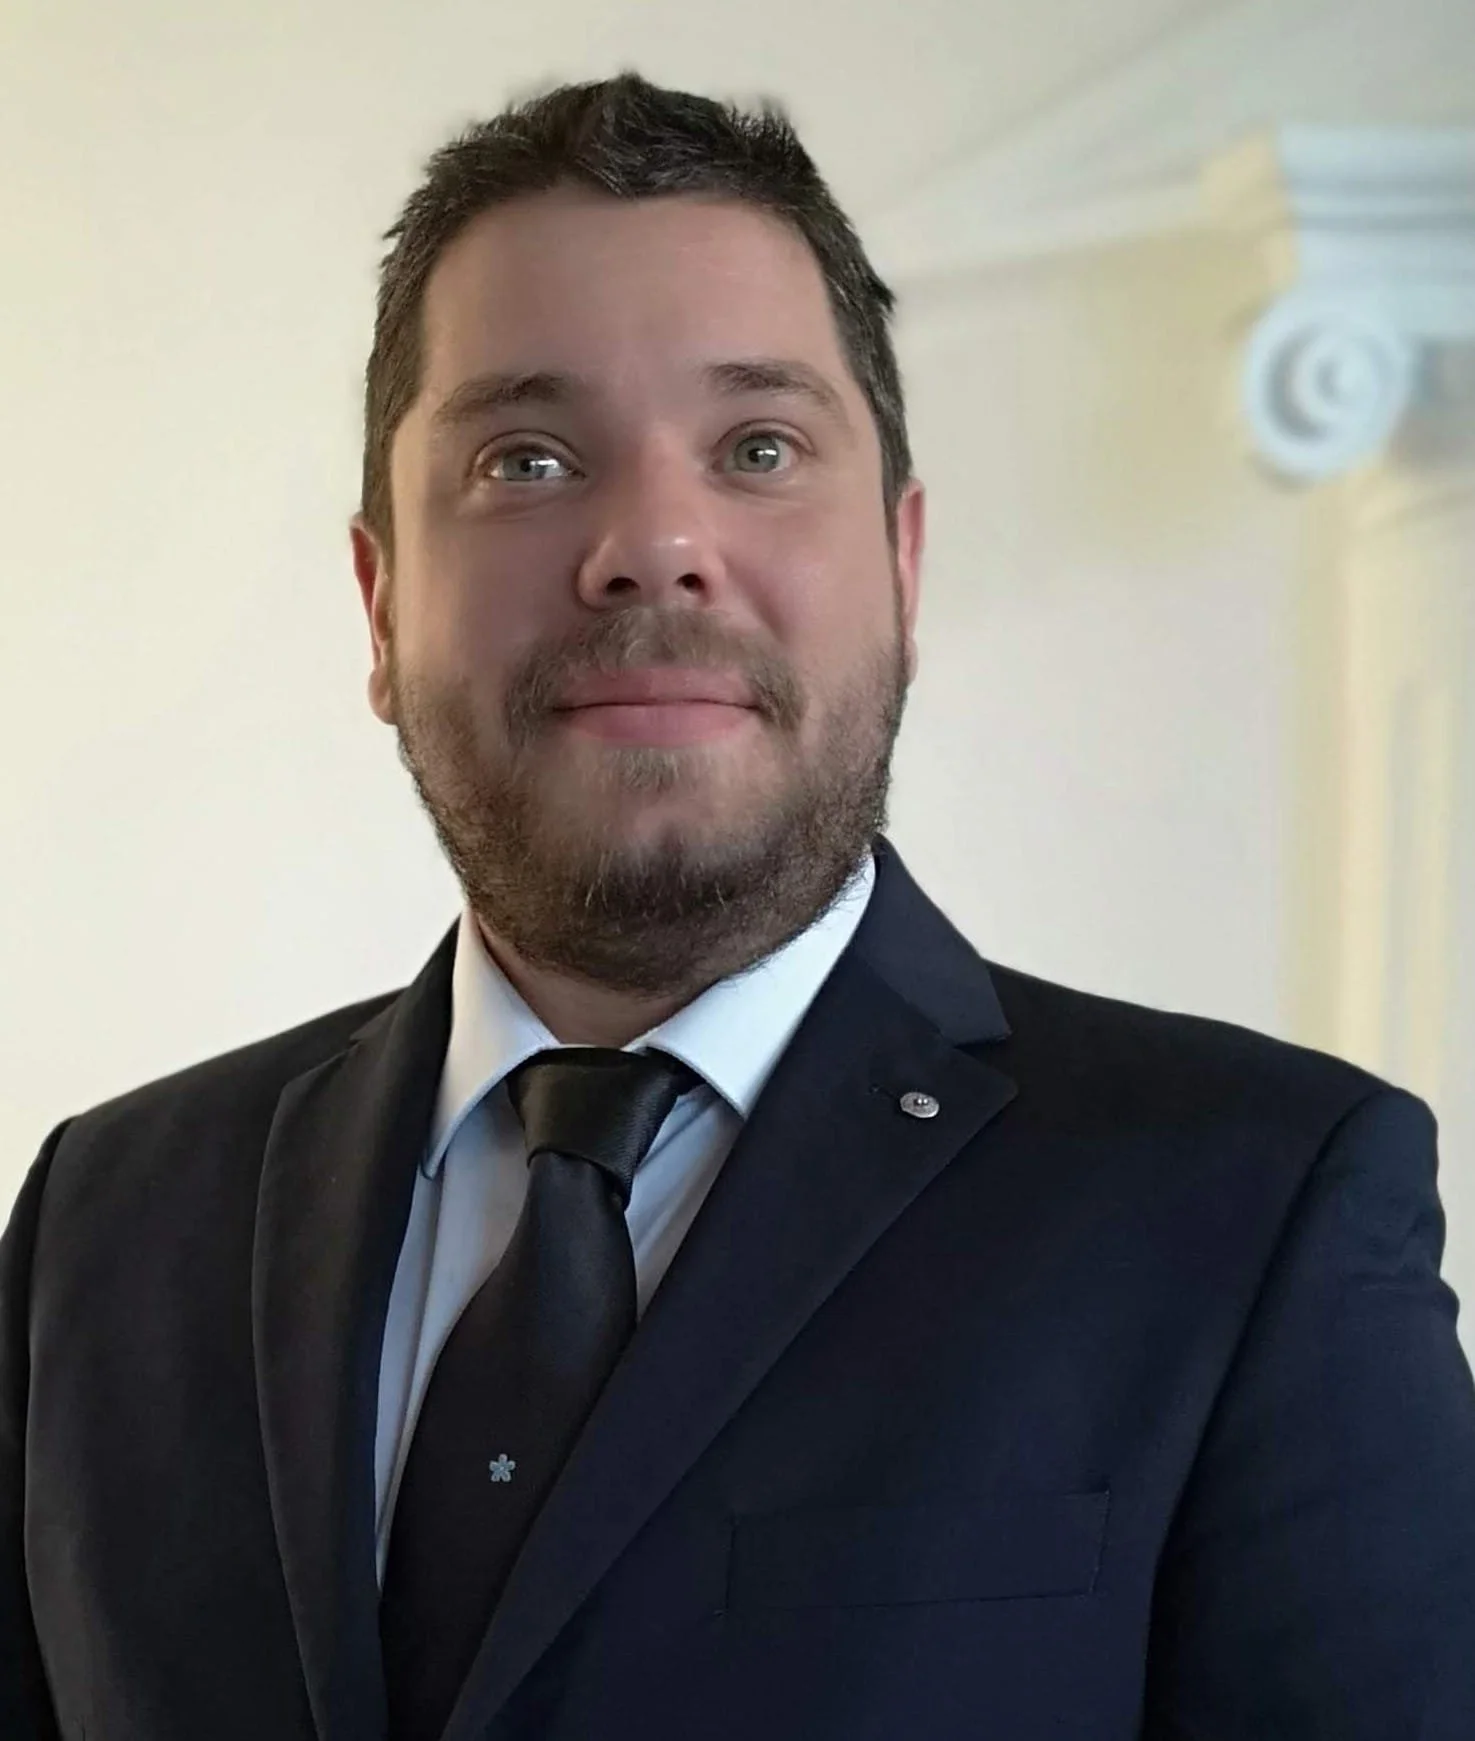
Meet Luca
I'm Luca, the mortgage and protection adviser behind Cambs Ely Mortgages.
I started Cambs Ely Mortgages with a straightforward idea: mortgage advice should be personal, understandable and built around the person rather than the product.
How much can you borrow? How much deposit do you need? Which lenders might consider your circumstances? Should you choose a two-year or five-year fixed rate? How long should your mortgage term be? What happens if you're self-employed? What if your credit history isn't perfect?
And even after you've found the right property, there are valuations, solicitors, mortgage applications, documentation and lender requirements to navigate.
My role is to help make sense of all of that.
I take the time to understand your circumstances, explain your options clearly and help you understand not only what I am recommending, but why.
You deal directly with me throughout your mortgage journey, from our initial conversation and Agreement in Principle through to the mortgage application and beyond.
Appointments are primarily held remotely, which means I can work with clients throughout England while still providing the personal service you would expect from a local adviser.
Mortgage Advice Without the Jargon
There is rarely a single mortgage answer that works for everyone.
Two people earning exactly the same amount of money could have very different mortgage options depending on their deposit, credit commitments, employment, credit history, property type and future plans.
That's why our approach starts with understanding you.
Understand First
Before looking at mortgage products, we need to understand the bigger picture.
That includes your income, deposit, existing commitments, credit history, property plans and what you want your mortgage to look like both now and in the future.
Research Properly
Different lenders have different criteria.
One lender may assess your circumstances very differently from another, particularly where self-employment, company income, variable earnings, credit history or an unusual property is involved.
We research suitable options based on your circumstances rather than relying on the criteria of a single bank or building society.
Explain Clearly
Finding a mortgage isn't enough.
You should understand what you're committing to.
We explain important considerations including the interest rate, monthly payments, mortgage term, fees, early repayment charges and other relevant features before you decide how to proceed.
Stay Involved
Our involvement doesn't end when the mortgage application is submitted.
We remain available throughout the process, helping with lender requirements, documentation and questions as your purchase or remortgage progresses.
Access to More Than 200 Lenders
Going directly to a bank generally means seeing the mortgage products and lending criteria available from that particular lender.
Working with a mortgage adviser can provide access to a much broader range of options.
Cambs Ely Mortgages has access to more than 200 lenders, including high-street banks, building societies and specialist lenders.
This can be particularly valuable because lenders don't all assess mortgage applications in the same way.
Your income structure, employment, credit history, deposit, age, property type and existing financial commitments can all influence which lenders may be suitable.
Our job is to understand those details and research suitable mortgage options based on your individual circumstances.
Who We Help
Mortgage advice isn't only for someone buying their first house.
We work with clients at many different stages of their property journey.
First-Time Buyers
Buying your first home can feel overwhelming when you've never been through the process before.
We can help you understand affordability, deposits, Agreements in Principle, mortgage products and the steps involved from starting your property search through to completing your purchase.
Home Movers
Moving home often means coordinating your existing mortgage, property sale and new purchase at the same time.
We can help you understand whether your existing mortgage may be portable, whether additional borrowing is required and what alternative mortgage options may be available.
Remortgage Clients
Your existing mortgage deal ending is an opportunity to review your mortgage rather than automatically accepting whatever happens next.
We can help you compare the options available through your existing lender with alternative remortgage options, taking account of costs, rates and your wider plans.
Self-Employed Clients & Company Directors
Being self-employed doesn't automatically make getting a mortgage difficult, but the way lenders assess income can vary considerably.
Whether you're a sole trader, contractor or company director, understanding how different lenders may assess your income can make a significant difference.
Landlords & Property Investors
Property investment can involve very different lending considerations from a residential mortgage.
We can help with Buy to Let, limited company Buy to Let, portfolio landlord mortgages, HMOs, holiday lets and other property finance requirements.
Clients With More Complex Circumstances
Not every mortgage application fits neatly into a standard box.
Previous credit problems, unusual income, short employment history, property type or other circumstances can sometimes mean that a more specialist approach is required.
Rather than assuming that something is impossible, we can investigate the available options and explain what may be achievable.
Commercial Property & Business Finance
Our work also extends beyond residential mortgages.
We can help business owners and property investors explore commercial mortgages, owner-occupied commercial finance, commercial investment mortgages, semi-commercial property finance, bridging finance, development finance and other business funding requirements.
Some forms of commercial and business finance are not regulated by the Financial Conduct Authority.
Mortgages Are Only Part of the Picture
Getting the mortgage is important, but it's also worth considering what would happen if life didn't go according to plan.
A mortgage can represent a substantial long-term financial commitment.
What would happen to that commitment if you died?
What would happen if you were diagnosed with a serious illness?
How would your household manage financially if illness or injury prevented you from working?
These aren't always comfortable questions, but they are important ones.
We can help you understand protection options including life insurance, critical illness cover and income protection.
Protection advice isn't simply about buying as much insurance as possible. It is about identifying the financial risks that matter to you, understanding any protection you already have and considering whether additional cover may be appropriate.
Protection can also be relevant to people who don't have a mortgage.
Rent, household bills and everyday living costs still need to be paid if illness or injury affects your ability to earn.
For business owners, we can also discuss business protection, including areas such as key person insurance, shareholder protection and relevant life insurance where appropriate.
Education Is an Important Part of Our Advice
We believe people make better financial decisions when they understand their options.
That's why education has become an important part of Cambs Ely Mortgages.
Our website contains an extensive library of mortgage, Buy to Let, commercial finance and protection guides covering many of the questions clients encounter throughout their financial journey.
We've also created our Educational Videos library, where mortgage, protection and property finance topics are explained in a straightforward and accessible way.
The objective is simple:
Understand before you decide.
Personal advice will always depend on your individual circumstances, but having a better understanding of the fundamentals can make conversations about your mortgage and protection much more valuable.
Explore Our Guides & Resources
Local Roots, Advice Across England
Cambs Ely Mortgages is based in Cambridgeshire.
We work with clients in Ely, Cambridge, Soham, Littleport, Newmarket and throughout Cambridgeshire and East Anglia.
However, mortgage advice no longer needs to be restricted by geography.
Our appointments are primarily conducted remotely, which allows us to work with clients throughout England.
Whether you're five minutes away or hundreds of miles away, you can speak directly with your adviser, share documents securely and progress your mortgage without needing to travel to an office.
That gives us the ability to combine the personal approach of a local mortgage adviser with the convenience of a modern, remote service.
Why Choose Cambs Ely Mortgages?
Choosing a mortgage adviser is about more than finding someone who can submit an application.
It's about finding someone you are comfortable asking questions, someone who takes the time to understand your circumstances and someone who can explain complex financial decisions in a way that makes sense.
At Cambs Ely Mortgages, our approach is built around:
Personal service — you deal directly with your adviser.
Clear explanations — we aim to explain mortgages and protection without unnecessary jargon.
Broad lender access — we have access to more than 200 lenders, including high-street and specialist lenders.
Individual research — recommendations are based on your circumstances and objectives.
Ongoing support — we remain involved throughout the mortgage process.
Education — we want you to understand the decisions you're making, not simply sign paperwork.
Frequently Asked Questions
Where is Cambs Ely Mortgages based?
Cambs Ely Mortgages is based in Cambridgeshire and works with clients locally in Ely, Cambridge and surrounding areas, as well as clients throughout England.
Do I need to live in Cambridgeshire to use your services?
No.
Appointments are primarily conducted remotely, which means we can work with clients throughout England.
Who will I deal with?
You'll deal directly with your mortgage and protection adviser throughout the process.
Our aim is to provide a personal service where you know who is dealing with your case and have someone you can contact when you have questions.
What happens during the first conversation?
The first conversation is about understanding you.
We'll discuss what you're trying to achieve, your income, deposit, existing commitments and any circumstances that may affect your mortgage options.
For buyers, this can also help establish an initial understanding of affordability and what the next steps may look like.
There is no expectation that you should already understand mortgages before speaking with us. Explaining the process is part of our job.
Do you charge a mortgage advice fee?
A fee may be payable for arranging your mortgage.
The amount depends on the circumstances and complexity of the case, and your adviser will explain the applicable fee before you choose to proceed.
Our mortgage arrangement fees are typically between £295 and £995.
Can you help me if I've already spoken to my bank?
Yes.
Speaking to your existing bank doesn't prevent you from speaking with a mortgage adviser.
Different lenders have different products and lending criteria, so reviewing the wider options available to you can still be worthwhile.
Can you help if I'm self-employed?
Yes.
We regularly help self-employed clients and company directors.
The way lenders assess self-employed income can vary, so understanding how your business and income are structured is an important part of researching suitable mortgage options.
What if I've had credit problems?
Previous credit problems don't automatically mean you cannot obtain a mortgage.
The type of credit issue, amount, age, whether it has been satisfied and your wider circumstances can all be relevant.
Different lenders also have different criteria, so it is important to understand the details before determining what options may be available.
Ready to Talk About Your Plans?
Whether you're preparing to buy your first home, moving house, approaching the end of your mortgage deal, investing in property, buying business premises or thinking about financial protection, the first step can simply be a conversation.
Tell us what you're trying to achieve and we'll help you understand what the next steps could look like.
Based in Cambridgeshire and helping clients throughout England through convenient remote appointments.
Building Blocks for a Brighter Future.
#BuildingBlocksForABrighterFuture
Your home may be repossessed if you do not keep up repayments on your mortgage.
The Financial Conduct Authority does not regulate some forms of Buy to Let, commercial mortgages and business finance.
Information on this page is for general information purposes and should not be considered personalised mortgage, protection, insurance, tax, legal or financial advice. Eligibility and the options available will depend on individual circumstances, lender criteria and, where applicable, insurer underwriting.